SOCPA Study Preparation
This podcast is designed to help accountants prepare for fellowship exams through an unconventional study method. Rather than relying on textbooks and highlighting, it uses engaging conversations to break down complex topics. Listeners are encouraged to build a logical framework for understanding concepts instead of memorizing them. The show focuses on SOCPA fellowship exam material and aims to make studying more interactive.
حلقات
Presentation & Changes [IFRS 18 / IAS 8] [S:1 E: Bonus 10]
Welcome to the Season 1 Grand Finale! 🎓 You’ve survived the long haul of the SOCPA Fellowship syllabus, and in this ultimate bonus session, we unite to give you the definitive exam-survival toolkit 🧰.This is not a theory lesson; it is a tactical breakdown of the classic traps examiners set under time pressure 🚨. We decode the high-stakes "Retrospective vs. Prospective" boundary of IAS 8 and patrol
Group Accounting [IFRS 3 / IFRS 10 / IAS 28] [S:1 E: Bonus 9]
This is the "Hardest Battle" of the SOCPA exam ⚔️. In this tactical survival bootcamp, we break down the "Unforgettable Framework" for Group Accounting 🏗️. We move past the deep theory of Episodes 26 and 28 to give you a mechanical, five-step algorithm designed to handle the most complex trial balances under extreme time pressure ⏱️.If you have ever panicked when seeing inter-company loans, fair v
Basic EPS vs Diluted EPS [IAS 33] [S:1 E: Bonus 8]
The Rapid-Fire Revision Clinic accelerates ⚡📊 into one of the most time-sensitive calculations on the SOCPA exam: IAS 33.This session focuses on the shortcuts and decision rules that determine which potential ordinary shares belong in Diluted EPS—and which must be ignored.Because the biggest time-waster in EPS questions is calculating instruments that turn out to be anti-dilutive.⸻Key subjects cov
Intangibles & Exploration [IAS 38 / IFRS 6] [S:1 E: Bonus 7]
The Rapid-Fire Revision Clinic continues ⚡📊—this time tackling two areas where timing determines everything: intangible assets and exploration assets.This bonus session focuses on the recognition gateways in: • IAS 38 • IFRS 6The central question in both standards is identical: when does an expenditure become an asset instead of an expense?⸻Key subjects covered in this session:• The Research Dead-
Provisions & Contingencies [IAS 37] [S:1 E: Bonus 6]
The Rapid-Fire Revision Clinic returns ⚡📊—this time covering one of the most conceptually asymmetric areas of the SOCPA syllabus: provisions and contingencies under IAS 37, along with the treatment of Saudi Zakat in IFRS-based financial statements.This session focuses on the recognition thresholds and the decision logic that determines whether an item becomes a liability, a disclosure, or nothing
Impairment & Recoverable Amount [IAS 36] [S:1 E: Bonus 5]
The Rapid-Fire Revision Clinic returns ⚡📉—this time targeting one of the most calculation-heavy areas of the SOCPA syllabus: IAS 36.This bonus session focuses purely on the math and journal mechanics behind impairment testing. The objective is simple: determine the Recoverable Amount, compare it with the Carrying Amount, and record the loss correctly—especially when revaluation reserves exist.⸻Key
Foreign Currency Translation [IAS 21] [S:1 E: Bonus 4]
The Rapid-Fire Revision Clinic returns ⚡📊—this time focused on the mechanics of multi-currency consolidation.In this technical bonus session 🎙️, we lock in the rules of IAS 21, moving beyond individual foreign invoices to the full translation of a foreign subsidiary into the parent’s reporting currency.The goal: eliminate confusion about which exchange rate applies where—and why translation differ
Financial Instruments [IFRS 9 / IAS 32] [S:1 E: Bonus 3]
This is not a drill. This is the Rapid-Fire Revision Clinic ⚡🧠 for the final sprint of SOCPA preparation.In this bonus session 🎙️ we lock in the mechanics behind financial instruments using the core framework of: • IFRS 9 • IAS 32The focus is simple: OCI vs. Profit or Loss and the mechanics of Amortized Cost.Because most exam mistakes happen when candidates mix these two areas.⸻Key subjects covere
Retirement Cost [IAS 19] [S:1 E: Bonus 2]
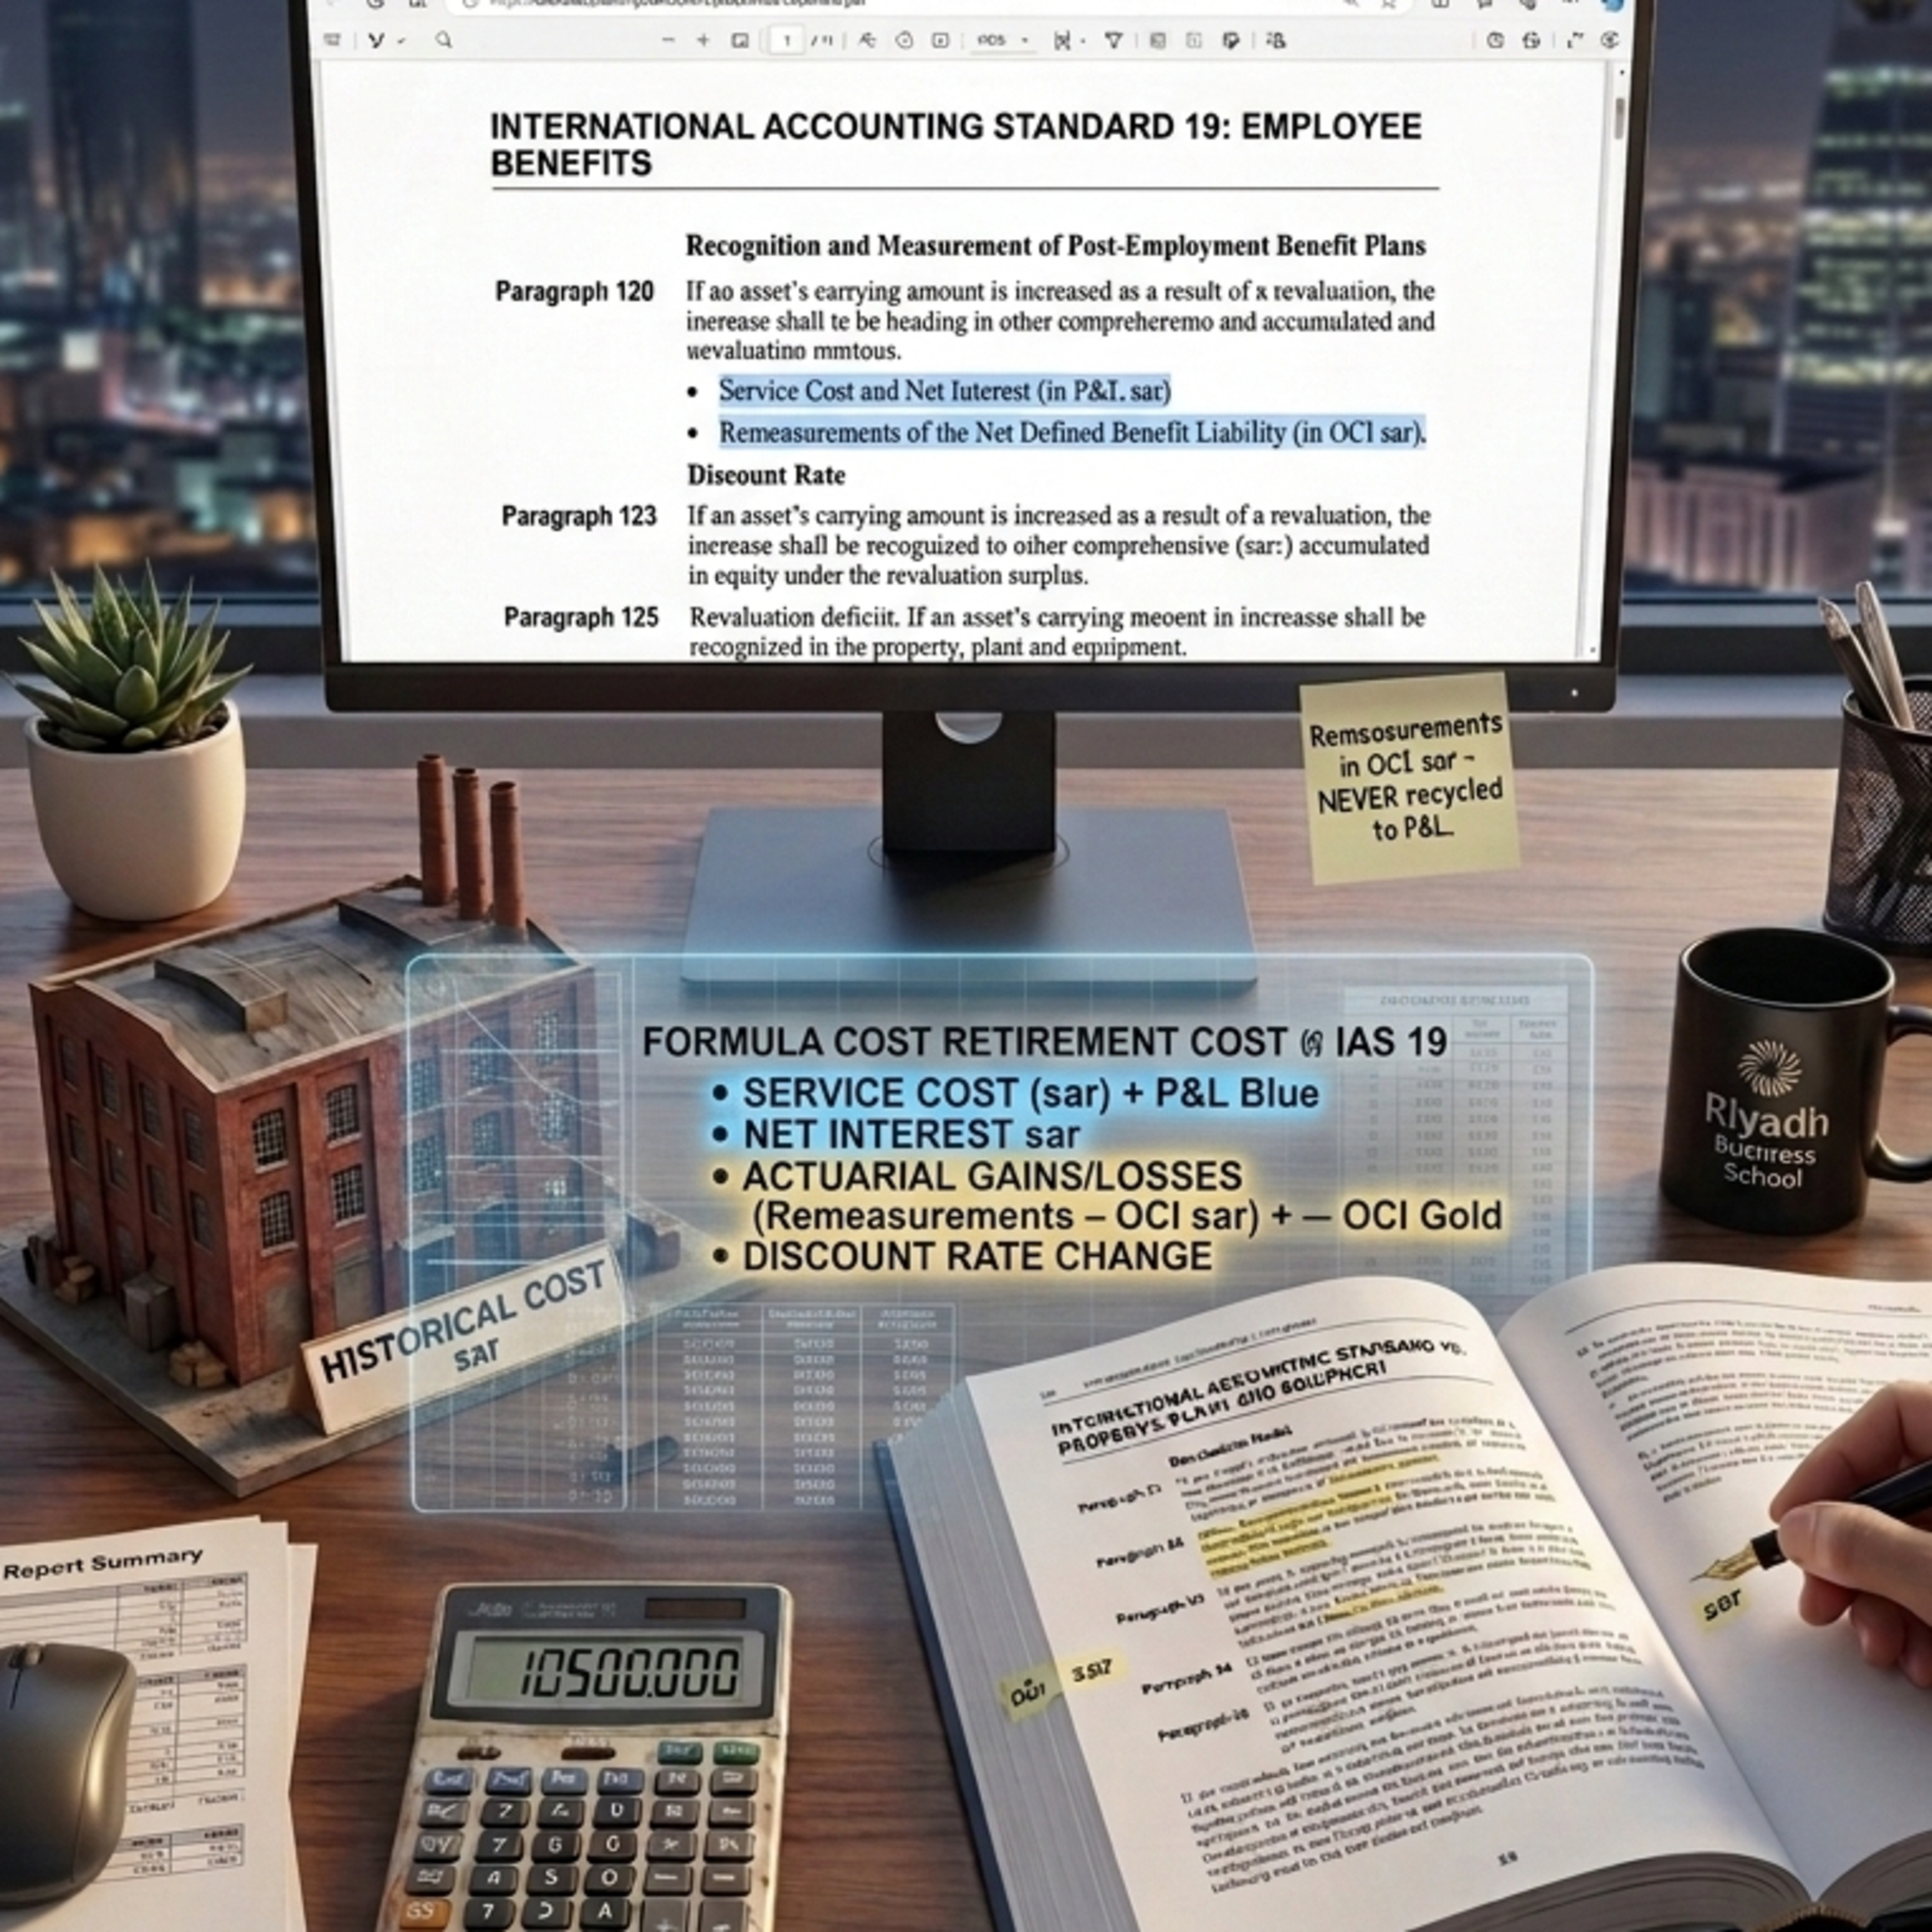
In this targeted bonus session 🎙️⚙️, we move beyond the theory of employee benefits and focus on the calculation mechanics behind IAS 19.Since the conceptual framework was covered earlier, this session becomes a workshop on dismantling a Defined Benefit note and rebuilding it correctly in the financial statements 📊.The objective is simple: separate what affects Profit or Loss from what stays perma
Revaluation Model [IAS 16] [S:1 E: Bonus 1]
In this high-intensity bonus episode 🎙️⚡, we strip away the fluff and focus purely on the mechanics of the IAS 16 Revaluation Model 🏗️📈.This isn’t just about “marking assets to market.” It’s about understanding the interaction between the Statement of Financial Position 📊 and the Statement of Profit or Loss 📉 when asset values change.We trace the full accounting lifecycle of a revaluation—from the
IFRS for SMEs 2024 Edition [S:1 E:33]
Why use 1,000 pages of rules when 250 will do? 📚✂️In this episode 🎙️, we unpack the 2024 Edition of IFRS for SMEs — the IASB’s streamlined framework for private entities.It aligns more closely with full IFRS (including concepts from IFRS 15 and IFRS 9) — but without importing their full complexity.For auditors in Jeddah and CFOs in Riyadh 🇸🇦, this is the new reporting baseline for many private com
Statement of Cash Flows [IAS 7] [S:1 E:32]
Profit is an opinion.Cash is a fact 💵.In this season finale 🎙️, we break down IAS 7 — the standard that reveals whether a business is truly generating liquidity or just accounting optimism.We move beyond accruals and into the real bloodstream of the company.⸻Key subjects covered in this episode:• The Three Buckets 🪣Every cash movement must fall into one of three categories:1️⃣ Operating Activities
Presentation of Financial Statements [IFRS 18] [S:1 E:31]
The “face” of financial reporting is changing 📊.In this episode 🎙️, we explore IFRS 18 — the new standard reshaping the structure of the Income Statement.For decades, presentation had flexibility.Now, categories are mandatory.⸻Key subjects covered in this episode:• The New Income Statement Categories 🗂️IFRS 18 introduces three mandatory categories:1️⃣ Operating2️⃣ Investing3️⃣ FinancingPlus separa
First-time Adoption of IFRS [IFRS 1] [S:1 E:30]
In this episode 🎙️, we step into one of the most consequential events in financial reporting: first-time adoption of IFRS.We break down IFRS 1 and explain why transitioning to IFRS feels like rewriting your company’s financial history 📚.Because the real starting point isn’t the first IFRS income statement.It’s the Opening IFRS Statement of Financial Position.⸻Key subjects covered in this episode:•
Financial Reporting in Hyperinflationary Economies [IAS 29] [S:1 E:29]
In this episode 🎙️, we step into one of the most extreme environments in financial reporting: hyperinflation 🔥📉.When a currency collapses, historical cost becomes meaningless. A building bought five years ago is recorded in “old money,” while today’s numbers are in “new money.” Comparability disappears.That’s where IAS 29 comes in.⸻Key subjects covered in this episode:• Identifying Hyperinflation
Consolidated Financial Statements [IFRS 3 /IFRS 10] [S:1 E:28]
In this episode 🎙️, we enter the high-stakes world of M&A and group reporting 🏢📊.We break down the Control Model under IFRS 10 and the acquisition mechanics under IFRS 3.Because consolidation isn’t about ownership percentage.It’s about power.⸻Key subjects covered in this episode:• Defining Control 🎯Under IFRS 10, control exists when three elements are present:1️⃣ Power over the investee2️⃣ Exposur
Financial Instruments [IFRS 9 / IFRS 7 / IAS 32] [S:1 E:27]
In this episode 🎙️, we demystify the alphabet soup of financial accounting 🧩📊.From simple bank loans 💳 to complex convertible bonds 📈, we break down the framework that governs how financial instruments are classified, measured, impaired, and disclosed under: • IAS 32 • IFRS 9 • IFRS 7Because in modern accounting, risk is just as important as profit.⸻Key subjects covered in this episode:• The “What
Investments in Associates and Joint Ventures [IAS 28 / IFRS 11] [S:1 E:26]
What happens when you own 30% of another company? 🤝📊You don’t control it — but you’re not passive either.In this episode 🎙️, we break down the Equity Method and the fine line between simple investing and strategic influence under IAS 28 and IFRS 11.Because 30% isn’t just a number — it changes the accounting completely.⸻Key subjects covered in this episode:• Significant Influence 🎯The famous 20% pr
Basis of Preparation of Financial Statements [IAS 8] [S:1 E:25]
What happens when you discover you’ve been depreciating an asset incorrectly for three years? 😬📉Or when the board suddenly changes the accounting philosophy of the company?In this episode 🎙️, we break down IAS 8 — the rulebook for fixing the past and adjusting the future.IAS 8 is about one core distinction:Are you rewriting history… or just updating expectations?⸻Key subjects covered in this episo
Exploration and Evaluation of Mineral Resources [IFRS 6] [S:1 E:24]
What do you do with millions spent drilling for oil 🛢️ or searching for gold 🪙 — before you even know if anything is there?In this episode 🎙️, we explore IFRS 6 — the standard that lives in the gray zone between hope and proof.Exploration accounting is about uncertainty. And IFRS 6 gives companies flexibility — but not a free pass.⸻Key subjects covered in this episode:• The Scope Boundary 🗺️IFRS 6
Related Party Disclosures [IAS 24] [S:1 E:23]
In business, relationships matter 🤝 — and in financial reporting, they matter even more.In this episode 🎙️, we unpack IAS 24 — the standard that forces companies to reveal transactions with insiders.Because a deal with your CEO’s family member is never just “normal business.” 👀⸻What we cover in this episode:• Identifying the Circle 🔍Who counts as a related party?It’s broader than most think:✔️ Par
Agriculture [IAS 41] [S:1 E:22]
What is a herd of cattle 🐄 or a palm grove 🌴 actually worth?In this episode 🎙️, we step into the unique world of IAS 41 — where nature meets fair value.Why is a sheep accounted for differently than the wool it produces? 🐑Because biological transformation changes value before your eyes — and IFRS wants that change reflected in profit.⸻Key subjects covered in this episode:• The Scope of IAS 41 🌾We d
Operating Segments [IFRS 8] [S:1 E:21]
Why do some companies bury weak performance in a “miscellaneous” bucket 🗂️ while others show you exactly where the money is made — or lost? 📉📊In this episode 🎙️, we unpack IFRS 8 — the standard designed to force operational transparency.This isn’t about textbook classifications. It’s about how management actually runs the business.⸻Key subjects covered in this episode:• The Management Approach 🧠IF
Interim Financial Reporting [IAS 34] [S:1 E:20]
In this episode 🎙️, we step into the world of “condensed” reporting 📄📉.Quarterly or half-yearly financial statements aren’t a 100-page annual report — but they must still present the truth. We break down IAS 34 and tackle the famous Discrete vs. Integral debate.Interim reporting is about discipline under time pressure.⸻What we cover in this episode:• The Concept of “Condensed” 📘IAS 34 allows short
Earnings per Share [IAS 33] [S:1 E:19]
What is a company’s profit actually worth per share? 📊💰In this episode 🎙️, we break down IAS 33 — the standard that translates total profit into a number that investors obsess over: Earnings Per Share (EPS).But EPS isn’t just division. Once dilution enters the picture, the math becomes strategic.⸻Key subjects covered in this episode:• Basic EPS 🧮Two components:👉 Numerator = Profit attributable to
Owners’ Equity [IAS 1 / IAS 32] [S:1 E:18]
In this episode 🎙️, we tackle the structural heart of Saudi business 🇸🇦🏗️.From the handshake of a General Partnership 🤝 to the layered equity of a Joint Stock Company, we walk through how ownership is formed, adjusted, and ultimately returned.We bridge the Saudi Companies Law with international standards like IAS 32 and IAS 1 to explain how capital is structured and presented properly 📊.Because eq
Government Grants [IAS 20] [S:1 E:17]
When the government gives a company financial support 💰🏛️, it’s not “free money” in accounting terms.In this episode 🎙️, we break down IAS 20 — and why you can’t just book a grant straight to income and move on.IAS 20 is built on one core idea: matching 📊.Grants follow the expenses they’re meant to compensate. No shortcuts.⸻What we cover in this episode:• Recognition Criteria ✔️Before recognizing
Foreign Operations and Foreign Currency Matters [IAS 21] [S:1E16]
What happens to your profit when the Riyal moves against the Euro? 💱📉In this episode 🎙️, we simplify the mechanics of foreign currency accounting under IAS 21.We go beyond memorizing exchange rates and dig into the deeper logic of functional currency — because if you misunderstand that concept, everything else collapses.Whether you’re booking one overseas supplier invoice 🌍 or consolidating a mult
Revenue from Contracts with Customers [IFRS 15] [S:1 E:15]
When do you officially “count” a sale? 🧾💰In this episode 🎙️, we break down the powerhouse standard: IFRS 15.Revenue is no longer about issuing an invoice or receiving cash. It’s about control — when it transfers, how it transfers, and what exactly was promised.From retail sales 🛍️ to multi-year construction contracts 🏗️, IFRS 15 applies the same five-step logic. Master the framework, and the compl
1.14: Events After the Reporting Period [IAS 10]
What happens when a major event occurs after year-end but before the financial statements are authorized for issue? ⏳📊Welcome to the gray zone of accounting — governed by IAS 10.This is where timing decides everything. Same event. Different classification. Completely different accounting outcome.⸻What we cover in this episode:• The Critical Timeline 🗓️The window between:👉 Reporting date (e.g., 31
1.13: Fair Value Measurement [IFRS 13]
What is an asset actually worth if you had to sell it today? 💰📉In this episode 🎙️, we decode the fair value puzzle under IFRS 13.We step away from historical cost 🧾 and into market-based exit prices — whether you’re valuing land in Riyadh 🏗️🇸🇦 or a complex financial derivative 📊.IFRS 13 doesn’t tell you when to use fair value — other standards do that.But it tells you how to measure it. And that “
1.12: Employee Benefits [IAS 19]
In this episode 🎙️, we simplify one of the most misunderstood standards in IFRS: IAS 19.We move beyond payroll 🧾 and dive into the heavy hitters 💣 — pensions 🏦, medical plans 🏥, and the Saudi-specific End of Service Benefits (EOSB) 🇸🇦.This is where accounting meets actuarial science 📊🧠 — and where many SOCPA candidates lose easy marks because they mix up P&L and OCI.⸻Key subjects covered in this e
1.11: Leases [IFRS 16]
In this episode 🎙️, we break down the standard that changed the Statement of Financial Position forever 📊⚡.We move away from the old Operating vs. Finance lease split for lessees ❌ and explain why almost every lease now creates a finance-style obligation 💳 under IFRS 16.Whether you’re leasing a fleet of delivery trucks 🚚 or a full office floor in Riyadh 🏢🇸🇦, this episode explains the logic, math,
1.10: Non-current Liabilities [IAS 1]
In this episode 🎙️, we zoom out from short-term liquidity stress and look at the long game 🏗️ — Non-Current Liabilities.These are the strategic obligations that fund expansion, acquisitions, and long-term growth 📈. From bond issuances 🏦 to pension deficits 👥, we break down how they’re recognized, measured, and—most importantly—classified under IAS 1.Because classification isn’t cosmetic. It shapes
1.09: Current Liabilities [IAS 1]
When an asset is no longer part of the long-term strategy 🚪, the accounting rules change immediately ⚡.In this episode 🎙️, we unpack IFRS 5 — the standard that forces companies to stop depreciating ⏹️ and start measuring assets for a fast exit 🚀.This is one of those standards examiners use to test whether you really understand timing and measurement… or you’re just memorizing rules.Key subjects co
1.08: Non-current Assets Held for Sale and Discontinued Operations [IFRS 5]
When an asset is no longer part of the long-term strategy 🚪, the accounting rules change immediately ⚡.In this episode 🎙️, we unpack IFRS 5 — the standard that forces companies to stop depreciating ⏹️ and start measuring assets for a fast exit 🚀.This is one of those standards examiners use to test whether you really understand timing and measurement… or you’re just memorizing rules.Key subjects co
1.07: Investment Property [IAS 40]
What happens when a company buys land 🌍 or buildings 🏢 just to earn rent 💵 or benefit from capital appreciation 📈?That property steps out of owner-occupied accounting and into IAS 40.In this episode 🎙️, we unpack the unique rules of Investment Property, with special focus on the strategic choice between the Cost Model and the Fair Value Model — and why that decision permanently changes how profit
1.06: Intangible Assets [IAS 38]
In this episode 🎙️, we step into the world of non-physical assets 👻💼.From software 💻 and licenses 📜 to brands 🏷️ and goodwill 🤝, we break down how companies decide what to capitalize 📈 and what to expense immediately 💥.This is where IAS 38 meets IAS 36 — the mandatory health check for assets you can’t see or touch 🔍.If you don’t understand this intersection, you’re guessing on half the exam questi
1.05: Property, Plant and Equipment [IAS 16,IAS 23, IAS 36]
How do you account for the “big stuff” 🏗️ — the buildings 🏢, machinery ⚙️, and land 🌍 that actually drive a business?In this episode 🎙️, we connect the dots between three critical standards that govern the life cycle of a physical asset — from its “birth” 👶, to its productive years 🔄, to a potential drop in value 📉.We move through: • IAS 16 (the backbone 🧱), • IAS 23 (interest during construction
1.04: Accounts Receivable
Managing what people owe you 💳 is just as important as making the sale itself 📈.In this episode 🎙️, we simplify the accounting for Trade Receivables and Notes Receivable, breaking down the rules around bad debts 🧾, impairment 📉, and even the secondary market for commercial paper 🏦.We anchor the discussion under IFRS 9 and the presentation rules in IAS 1 — because this topic is more technical than
1.03: Inventory [IAS 2]
In this episode 🎙️, we tackle one of the most material items on the Statement of Financial Position 📊: Inventories 📦 under IAS 2.Whether it’s raw materials 🧱, work-in-progress ⚙️, or finished goods 🏷️, how you value these items directly impacts your profit 📈.For SOCPA candidates 📝 and accounting pros 💼, this standard is all about the “Golden Rule” of valuation — and knowing exactly which costs bel
1.02: Cash and cash equivalents
It’s the most liquid asset on the Statement of Financial Position 💧📊, but also the most vulnerable ⚠️. In this episode 🎙️, we break down the essentials of Cash and Cash Equivalents 💵💳. Whether you are balancing a petty cash tin 🪙 or reconciling a complex multi-currency bank statement 🌍💱, we cover the controls 🔐 and reporting standards 📚 you need to know for the SOCPA exam 📝 and beyond 🚀In this epi
1.01: Conceptual Framework
Why do we record assets at cost? 💰What makes information “relevant”? 🎯In this episode 🎙️, we go back to basics — but not the easy kind. We’re breaking down the Conceptual Framework for Financial Reporting 📚 under IFRS Conceptual Framework.This is the foundation for everything in the SOCPA and IFRS world 🌍.If you truly understand the “why” behind this framework 🧠, you won’t need to memorize the “ho